How much could I borrow?
Try a broad borrowing illustration using income and regular commitments. It does not include your deposit or confirm a lender's decision.
Explore borrowing
Your home may be repossessed if you do not keep up repayments on your mortgage.
Budget 2026 confirmed an England-only scheme for some first-time buyers purchasing a participating new build, with a 20% equity loan and a 2.5% minimum deposit. Pre-registration is expected by the end of December 2026, with full applications from February 2027.
Important: this does not guarantee a mortgage or eligibility. Income caps, local property-price caps, lender and developer participation still apply, and the formal delivery arrangements need to be in place.
Read the full factual update
At a glance
A 20% equity loan, 2.5% minimum deposit, five-year interest-free period and income caps of £110,000 outside London and £140,000 in London.
The local-authority price cap, participating developers and lenders, annual funding availability and the formal scheme rules.
Checked against HM Treasury Budget 2026 on 28 October 2026.
Buying or remortgaging can feel like a lot. Start with the questions that matter to you and take time to understand the options before deciding what to do next.
Start with how much you might borrow, how much cash you need and what the mortgage could cost each month. You can use every tool without leaving your contact details.
Try a broad borrowing illustration using income and regular commitments. It does not include your deposit or confirm a lender's decision.
Explore borrowingEstimate a deposit plus common buying costs, including Stamp Duty, legal work and surveys. These are assumptions, not quotes for your purchase.
Estimate buying costsUse a loan amount, interest rate and term to estimate repayments and total interest. The illustration keeps the same rate throughout and excludes fees.
Calculate monthly paymentsCheck an estimate for a purchase in England, including first-time buyer relief where you qualify. The result depends on your circumstances.
Check Stamp DutyImportant: These are illustrations, not mortgage offers, quotes or lending decisions. Your circumstances, the property and the lender's criteria all matter. If you have figures in mind, we can talk through what they mean for you.
You do not need to have every answer before we talk. Bring the figures you have, and we can work through the questions together.
Here's an overview of the typical steps involved in buying your first home.
We discuss your income and deposit to understand what you might be able to afford.
I can help you apply for a Decision in Principle, which shows estate agents you've been assessed for a mortgage.
You go house hunting. Once you find a property and have an offer accepted, I handle the full application.
I liaise with lenders and solicitors to help keep things moving towards completion.
Click each step below to see what typically happens at each stage.
We start with a friendly, no-pressure conversation about your situation. This can be over the phone, video call, or in person at my office in Alsager.
This usually takes about 30-45 minutes. There's no charge and no obligation.
A Decision in Principle (also called an Agreement in Principle or Mortgage in Principle) is a certificate from a lender indicating they would, in principle, consider lending you a certain amount.
Estate agents often prefer to see a DIP as it shows you've been assessed for a mortgage. It's not a guarantee of lending, but it can help when making offers.
Timescales vary depending on the lender.
With a clearer idea of your budget, you can start viewing properties with more confidence.
If you're unsure whether a property is within your budget, or want to discuss how an offer price might affect your monthly payments, feel free to get in touch. I'm happy to run through the numbers with you.
This stage varies — some people find their home in weeks, others take months. There's no rush.
Once your offer is accepted, we move to the full mortgage application. This is where I do most of the work on your behalf.
Application and decision times vary with the lender, documents, valuation and any further checks.
The lender assesses the property's value and suitability as security for the mortgage. Its valuation is not a detailed condition survey; you may want a separate survey for your own benefit.
Confirms the property value for the lender. Doesn't check condition in detail.
Suitable for standard properties. Highlights any obvious issues.
Often recommended for older or unusual properties. Very thorough.
Valuation timing depends on the lender, property and whether an inspection is needed.
If the lender is satisfied with the valuation and your application, they'll issue a formal mortgage offer. This is an important milestone.
Check the offer expiry date and speak to the lender if your circumstances or completion date change.
Your solicitor handles all the legal paperwork. This is often the longest part of the process, but I'll help keep things moving where I can.
Typically 6-10 weeks, but can be longer if there are complications.
Conveyancing is not regulated by the Financial Conduct Authority.
The final stage. Exchange of contracts makes the sale legally binding, and completion is when you get the keys.
Congratulations — you're a homeowner!
If you're finding it difficult to save a large deposit, there are several government-backed schemes that may be worth exploring.
Please note: Government schemes and their terms change regularly. The information below is a general overview only. Please verify current eligibility criteria and terms on gov.uk before making any decisions.
Buy a share of your home (often 10%-75%) and pay reduced rent on the rest. This may suit those with a smaller deposit or lower income.
New-build homes offered at a discount for local first-time buyers and key workers. The discount stays with the property.
The Mortgage Guarantee Scheme encourages lenders to offer 95% mortgages. You may only need to save a 5% deposit.
Save towards your first home and receive a government bonus. Must be used for first home (subject to price limits) or retirement.
Not sure which scheme might suit your situation? I can help you understand your options.
Discuss My OptionsThe scheme information above is for general guidance only and may not reflect the latest terms or eligibility criteria. Government schemes are subject to change. Always verify details on gov.uk before making decisions. Your home may be repossessed if you do not keep up repayments on your mortgage.
Gather these documents before we chat and you'll be ready to move fast when you find the right home.
Must be current and not expired
💡 A passport is preferred by most lenders
Utility bill, bank statement, or council tax bill
💡 Mobile phone bills usually aren't accepted
Consecutive months showing your regular income
💡 Include any bonus or overtime if it's regular
Shows your annual earnings and tax paid
💡 You get this from your employer each April
Required if you've been in your job less than 3 months
💡 Shows your salary and employment terms
All accounts where your salary is paid or savings held
💡 Lenders look at your spending habits, so avoid gambling transactions
Shows where your deposit money came from
💡 If it's a gift, you'll need a signed letter from the giver
Address, price, and estate agent contact
💡 I can help before you've found a property too
Their name, firm, and contact information
💡 I can recommend local solicitors if you need one
I live and work here. Here's what you need to know about buying your first home in our town.
Property prices and trends change, and online averages do not tell the whole story. I can talk through what current asking prices, your deposit and your budget may mean for your own plans.
Direct trains to Crewe, Stoke, and Manchester. Easy access to M6.
Compare homes using their asking price, condition and likely running costs, alongside your deposit and monthly budget.
Well-regarded primaries and Alsager School is a popular secondary choice.
Alsager Mere, Milton Park, and surrounding countryside. Perfect for dog walkers and families.
Local butchers, bakeries, cafés, and pubs. Real community feel without being isolated.
New developments bringing young families. Active community groups and events throughout the year.
It's normal to have questions. These answers explain the starting points, without assuming everyone's situation is the same.
There is no single deposit requirement for everyone. It depends on the mortgage, lender and any scheme you use. As an illustration, 5% of a £200,000 home is £10,000 and 10% is £20,000. Those are examples, not minimum requirements or confirmation that you qualify. You also need to budget for buying costs alongside the deposit.
Lenders assess your income, regular commitments, credit history and other circumstances. An income multiple alone cannot confirm your budget. The borrowing calculator gives a broad illustration using simple assumptions; it does not include your deposit or replace a lender's assessment.
Alongside the deposit, allow for legal work, searches, surveys, moving costs and any mortgage fees. Stamp Duty may also apply, depending on the purchase and whether you qualify for relief. Get quotes for your own purchase rather than treating calculator allowances as fixed prices. My mortgage advice is fee-free for standard cases: the lender pays a commission when the mortgage completes. A fee may apply for complex cases, which I explain upfront.
There is no guaranteed completion time. The lender's checks, valuation, legal work, property and any chain all affect the timeline. A mortgage offer is one step in the process, not confirmation that you can move in. Your solicitor can explain what remains before exchange and completion.
A smaller deposit may be possible, but eligibility depends on the lender, mortgage, property and any scheme rules. A 5% deposit on a £200,000 home would be £10,000, purely as an example. Having that sum does not guarantee a mortgage. We can look at the deposit alongside your income, commitments and buying costs to understand your options.
Understanding your likely budget before house hunting can help. A Decision in Principle is a lender's initial indication, not a formal mortgage offer or guarantee of approval. Ask what credit check the lender will carry out before applying: some use a soft search and others a hard search. A full application also involves checks on you and the property.
I can help you understand the process and compare options from a comprehensive lender panel, based on your circumstances. I also help with the application and communication with the people involved. I'm based in Alsager and support first-time buyers across Cheshire. Suitability and lending decisions depend on your circumstances and the lender's criteria.
Check your mortgage offer, statement or lender app for the deal-end date and what happens next. Without a new arrangement, you may move onto the lender's reversion rate, often called its Standard Variable Rate. Review your options before the deal ends, allowing time for any application. Check early repayment charges and the completion date before switching; a new deal is not guaranteed to cost less.
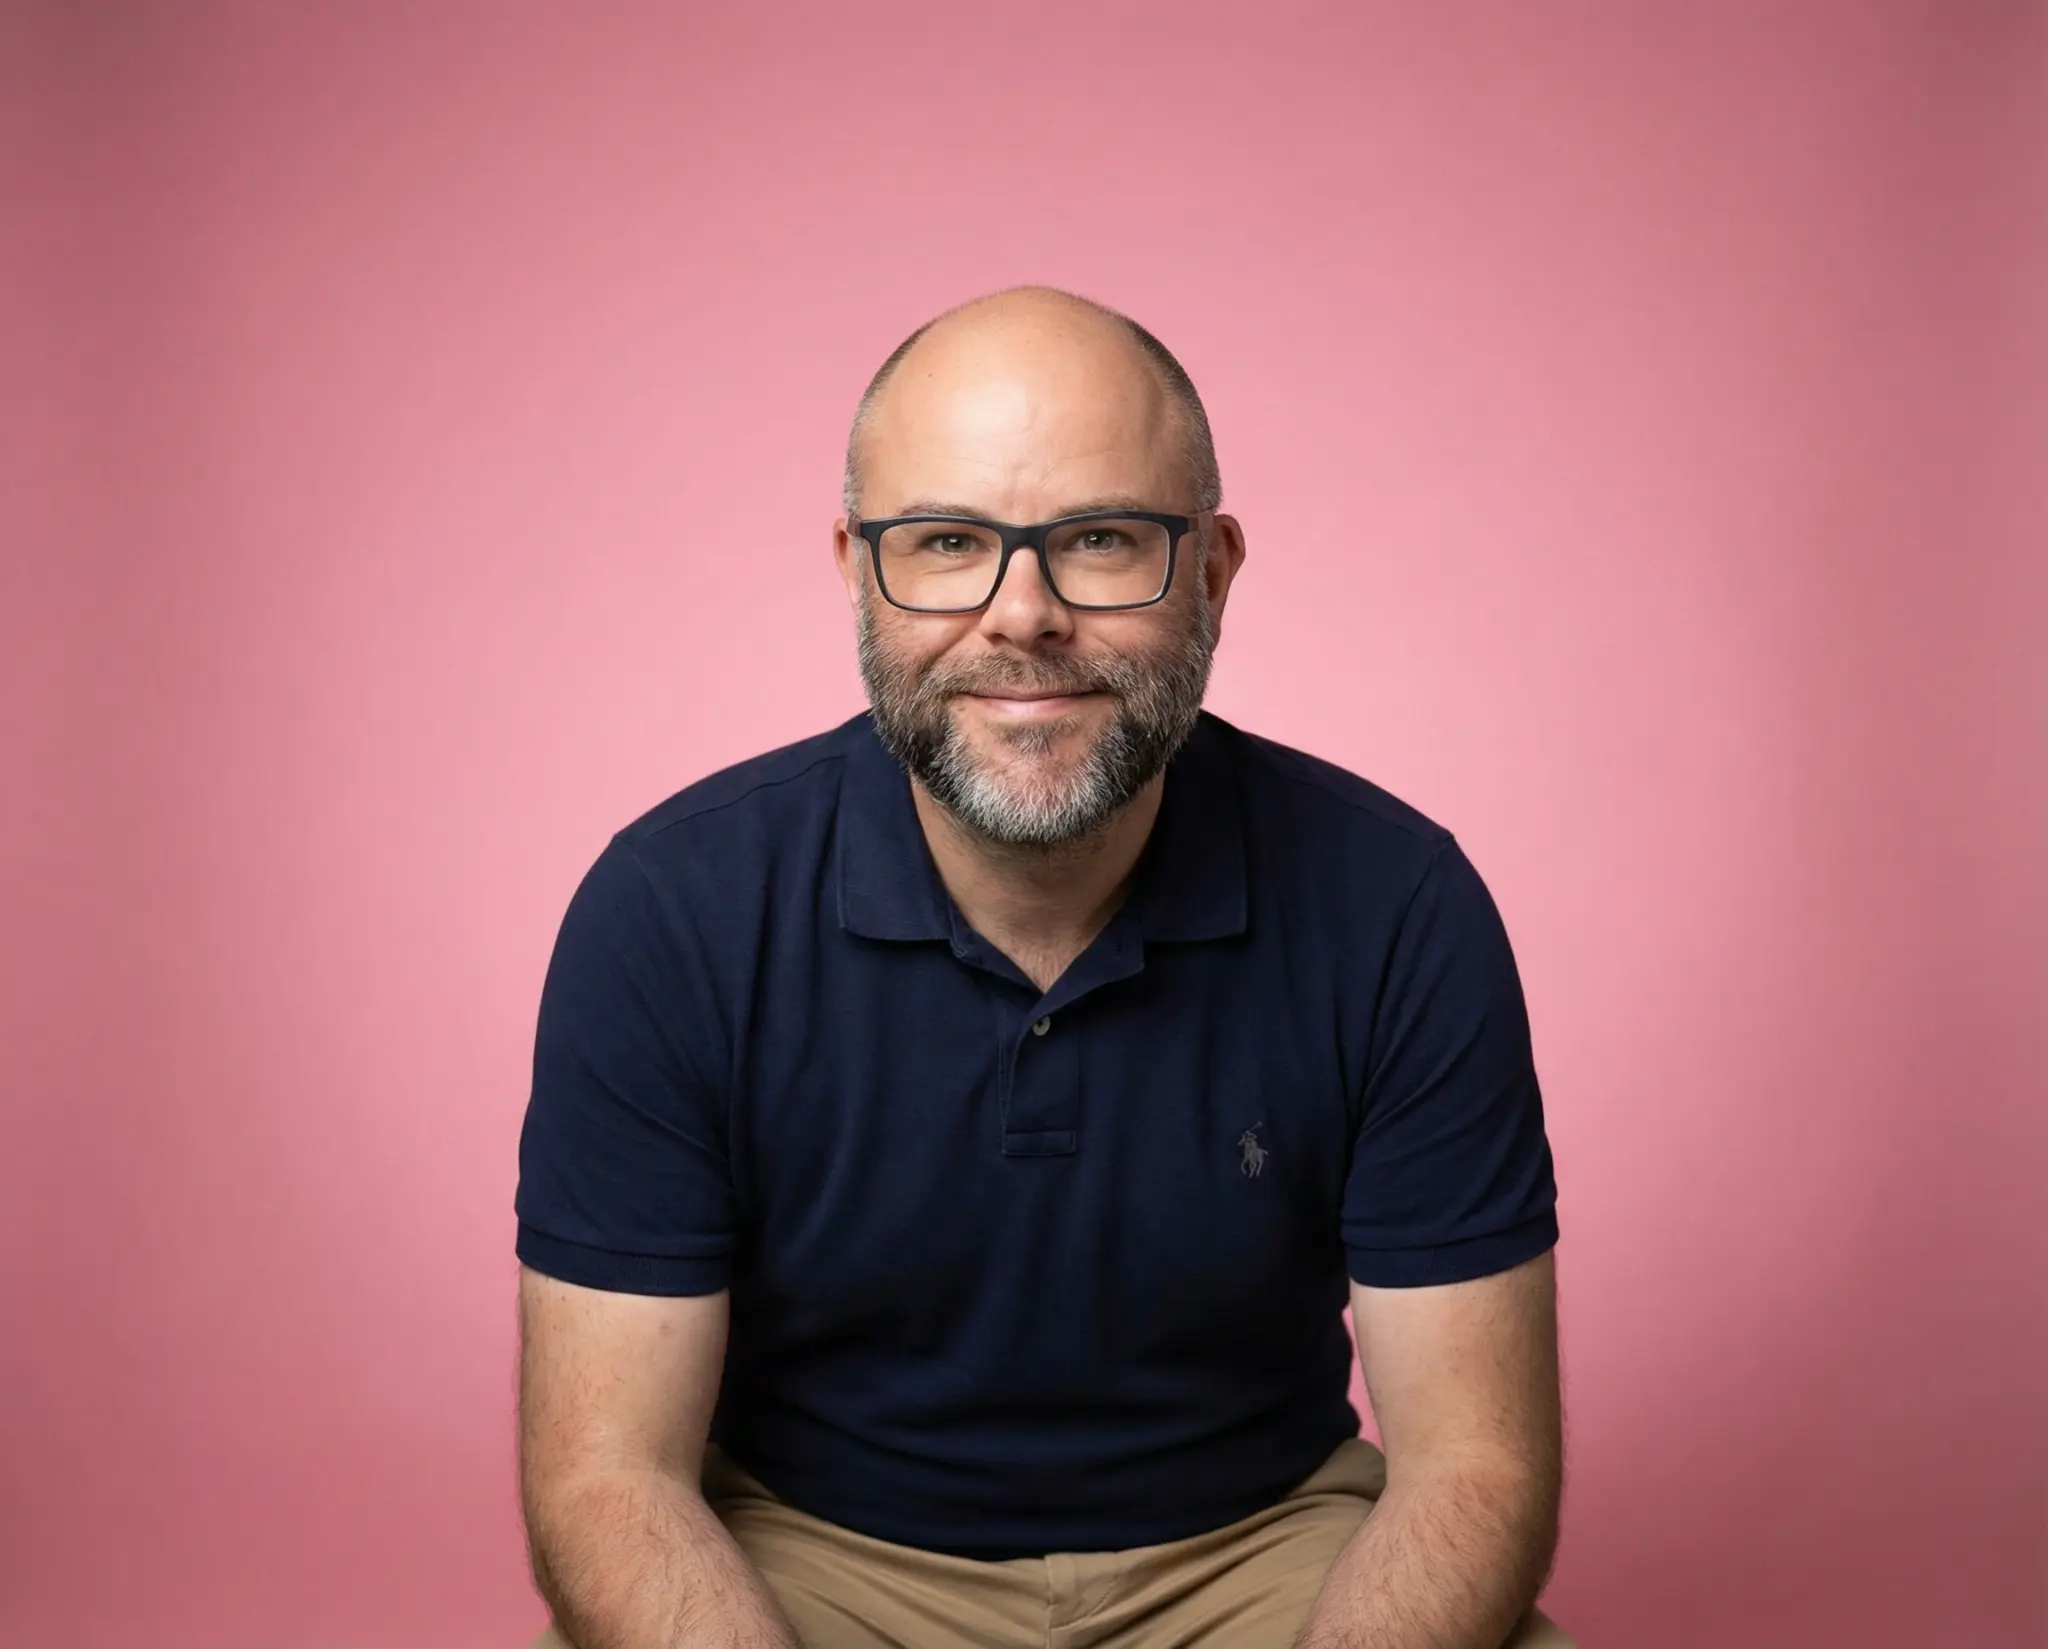
Rob Davies
Your local mortgage adviser in Alsager
You don't need to have found a house yet. In fact, it can be helpful to chat before you start looking.
Get a clearer idea of what you might be able to borrow, so you can focus on properties within reach.
I can help you apply for a Decision in Principle certificate to show estate agents.
No question is too basic. I'm here to explain everything in plain English.
Mortgage answers
Clear answers for people getting ready to buy their first home.
Last verified 28 October 2026
A 2.5% deposit is the announced minimum for eligible Your First Home purchases, not a guarantee that a buyer or property will qualify.
Read answerLast verified 28 October 2026
Budget 2026 confirmed the main design and timetable for Your First Home, but it does not guarantee a mortgage, eligibility or a property purchase.
Read answerLast verified 28 October 2026
The new First Time Buyer ISA is planned from April 2029 for new savers, with £4,000 yearly contributions and a 25% Government bonus for qualifying first homes up to £450,000.
Read answerA calmer next step
A short, informal conversation to help you understand your options. Most people use it to sense-check where they are.